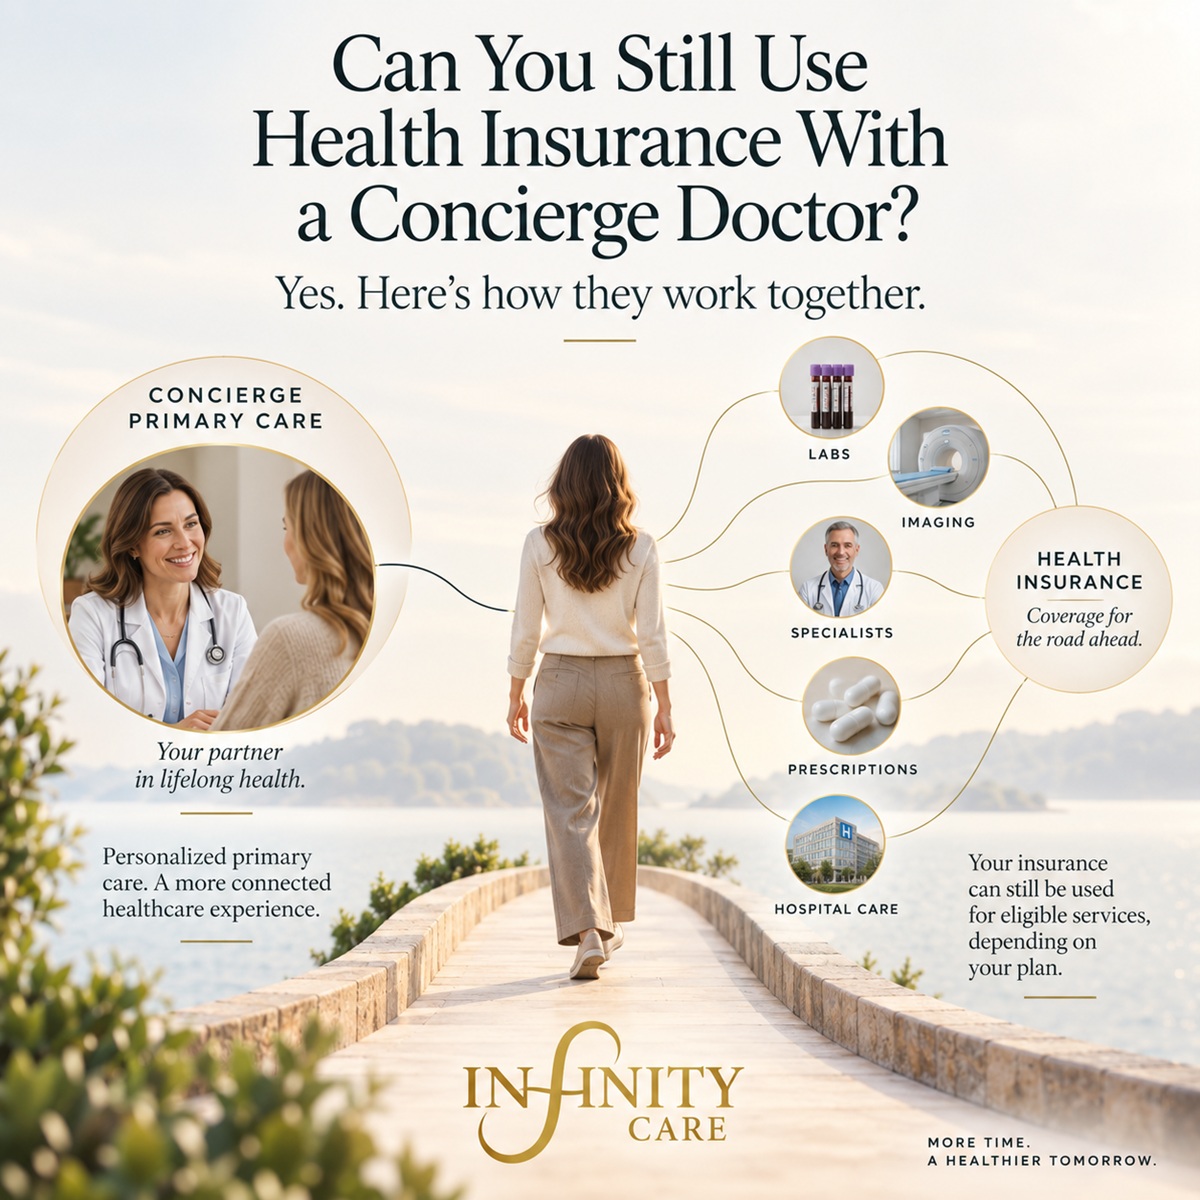
Yes. In many cases, patients with a concierge doctor can continue using health insurance for eligible outside services such as laboratory testing, diagnostic imaging, prescriptions, specialist care and hospital services, depending on the terms of their individual health plan.
Choosing a concierge primary care physician does not necessarily mean giving up your health insurance or paying out of pocket for every aspect of your healthcare. In fact, health insurance and concierge medicine can serve two very different—and complementary—purposes.
At Infinity Care, understanding that distinction can help patients make informed decisions about both their healthcare and their healthcare spending.
Concierge Medicine and Health Insurance Are Not the Same Thing
In a concierge medical practice, patients typically pay a membership fee directly to the practice in exchange for an enhanced primary care experience. Depending on the practice, this may include longer appointments, greater physician availability, more personalized preventive care, easier communication, and more comprehensive coordination of care.
Health insurance, meanwhile, may continue to cover eligible healthcare services obtained outside of the concierge practice according to the patient’s individual insurance plan.
In other words, your concierge membership and your health insurance can work alongside one another.
A physician does not necessarily have to bill your insurance for office visits in order for you to maintain and use health insurance for other covered medical services.
Can a Concierge Doctor Order Blood Work That Goes Through Insurance?
Often, yes.
A concierge physician can order laboratory testing just as other physicians do. Depending on your insurance plan and the laboratory you choose, eligible testing may be billed to your health insurance by the laboratory.
For example, your concierge physician may order:
- A complete blood count (CBC)
- Cholesterol testing
- Hemoglobin A1c
- Thyroid testing
- Kidney and liver function tests
- Iron studies
- Vitamin levels
- Urine testing
- Other diagnostic or preventive laboratory testing when medically appropriate
The laboratory—not necessarily your concierge physician—is the entity performing the test and billing for that service.
Your ultimate out-of-pocket cost will depend on factors such as your insurance benefits, deductible, laboratory network and whether the particular test is covered.
Can a Concierge Doctor Order an MRI, CT Scan, Ultrasound, or X-Ray?
Yes. Concierge physicians can order medically appropriate diagnostic imaging.
This may include:
- MRI
- CT scans
- Ultrasounds
- X-rays
- Bone density testing
- Other diagnostic imaging
The imaging center or hospital typically bills for the imaging service. If the facility participates with your insurance and the study meets your plan’s coverage requirements, your insurance may cover some or all of the cost according to your benefits.
Some imaging studies may require prior authorization from your insurance company before they are performed. Coverage requirements vary considerably among insurers and individual plans.
Can a Concierge Doctor Order Mammograms and Preventive Screenings?
Your concierge physician can also order appropriate preventive screening, including mammography and other recommended tests.
Whether a particular screening service is covered—and whether you have a copay, coinsurance or deductible—depends on your health plan and the circumstances under which the test is ordered.
This is an important distinction: the fact that your primary care physician practices under a concierge model does not automatically make an outside test a cash-pay service.
Can You Use Health Insurance for Prescriptions From a Concierge Doctor?
The same general concept can apply to prescriptions.
A concierge physician can prescribe medications, and patients may generally use their prescription drug benefits when filling those prescriptions, subject to the rules of their individual health plan.
Depending on the medication, an insurer may require a prior authorization, step therapy, quantity limits or other coverage criteria.
Your concierge membership does not replace prescription drug insurance. Rather, the physician who knows your medical history and treatment goals can help determine which medications are clinically appropriate and, when possible, consider cost and coverage as part of the treatment decision.
Can a Concierge Doctor Refer You to Specialists?
Patients with concierge physicians can still see specialists and use their health insurance for eligible specialist care.
A concierge primary care physician may refer a patient to a cardiologist, gastroenterologist, dermatologist, orthopedist, endocrinologist or another specialist when appropriate.
Whether the specialist is covered depends on the patient’s insurance network and plan requirements—not simply on whether the referring primary care physician operates a concierge practice.
One of the potential advantages of concierge primary care is having a physician who can help coordinate this care: determining when specialty evaluation is appropriate, communicating relevant medical history, reviewing outside recommendations and helping the patient understand how the pieces of their care fit together.
Why Keep Health Insurance If You Have a Concierge Doctor?
Concierge medicine is generally not a substitute for health insurance.
Even with comprehensive primary care, patients may still need services such as:
- Emergency department care
- Hospitalization
- Surgery
- Specialist care
- Advanced diagnostic testing
- Imaging
- Prescription medications
- Cancer treatment
- Rehabilitation or physical therapy
- Other costly medical services
Health insurance provides financial protection for these types of healthcare expenses according to the terms of the patient’s plan.
A helpful way to think about the relationship is this:
Concierge medicine supports how your primary care is delivered. Health insurance helps pay for covered healthcare services and protects against larger medical expenses.
For many patients, the two can complement each other.
An Added Benefit: More Choice in How You Pay for Certain Services
Having insurance does not always mean that using insurance is automatically the least expensive option for every service.
For certain laboratory tests, imaging studies or medications, a transparent cash-pay price may sometimes be less expensive than the amount a patient would ultimately pay through a high-deductible insurance plan.
That means patients may occasionally have a choice.
For example, a patient may be able to compare:
Insurance: Have the outside laboratory or imaging facility submit the service to insurance and pay the applicable deductible, copay or coinsurance.
Cash pay: Pay a transparent self-pay price when one is available and appropriate.
The better option can vary by test, facility and insurance plan.
This flexibility can be particularly valuable for patients with high-deductible health plans. It allows healthcare decisions to consider not only what testing is medically appropriate, but also how that testing can be obtained in a financially sensible way.
Patients should keep in mind that services paid for outside of insurance may not count toward their deductible or out-of-pocket maximum.
A Real-World Example
Imagine that during a comprehensive visit, your concierge physician determines that you need blood work, a mammogram and an MRI.
Your physician can order all three.
You might have your blood drawn at a laboratory that participates with your health plan and have the laboratory submit the testing to insurance.
You might schedule your mammogram at an in-network imaging center and use your insurance benefits for the study.
If your MRI requires prior authorization, the necessary authorization process may need to be completed before the imaging center performs the study.
Meanwhile, the time you spend with your concierge physician—the detailed evaluation, discussion of your health, preventive strategy and ongoing primary care relationship—is provided according to the concierge practice’s membership model.
The two systems can coexist.
The Bigger Picture: Concierge Medicine Doesn’t Mean Navigating Healthcare Alone
One misconception about concierge medicine is that choosing a physician who does not bill insurance means stepping outside of the traditional healthcare system altogether.
That isn’t necessarily the case.
A concierge physician can remain at the center of a patient’s care while the patient continues to use insurance for eligible services throughout the broader healthcare system.
The difference is that patients can have a primary care physician helping them navigate that system—ordering appropriate testing, coordinating specialty care, reviewing results and helping determine what should happen next.
Concierge Medicine in Westport, Connecticut
Infinity Care is a concierge primary care practice serving adults in Westport and the surrounding Fairfield County community.
Our model is designed around a more personalized physician-patient relationship, with longer visits, greater accessibility, thoughtful preventive care and coordination across the healthcare system.
While Infinity Care does not bill health insurance for membership-based primary care services, patients may still maintain and use their health insurance for eligible outside services such as laboratory testing, diagnostic imaging, specialist care, prescriptions and hospital services, subject to the terms of their individual insurance plans.
Concierge medicine and health insurance don’t have to be an either-or decision. For many patients, they can work together—combining personalized primary care with the financial protection and broader coverage of health insurance.
It’s an opportunity to meet Dr. Kofler, ask questions about the practice, and discuss what you’re looking for in your primary care relationship.